

Preface: We can’t understand the evolution and adaptions (successful or otherwise) or economic systems unless we place supply chains at the heart of the analytical enterprise. I have tried to do precisely this in my books — China, Trust and Digital Supply Chains (2023) and more recently Thermoeconomics in a Time of Monsters, and its companion “practitioners’ handbook” The Provenance Economy (both 2026). This essay seeks to bring some of this work together in a shorter, summary form, while also extending it as a means of framing how scarcity and inflation propagate through systems via supply chain linkages. In doing so, it is worth keeping in mind the essay on Oil Shock Propagation and Nested Supply Chains, which I wrote to explore ways of analysing the variable impacts of the closure of the Strait of Hormuz on different “ideal type” energy-economic systems.
The world economy seems increasingly defined by disruption. Pandemic lockdowns, wars, sanctions, droughts, semiconductor shortages and energy crises have all revealed a common reality. That is, disturbances do not remain where they originate. They spread.
A disruption in one place becomes a price increase elsewhere. I speak of contagion propagation. A shortage in one industry creates bottlenecks in another. Rising costs squeeze margins, alter investment decisions and reshape patterns of consumption. These effects ripple through economies over months and years, sometimes dampening, sometimes amplifying, but rarely disappearing without consequence.
Yet conventional economics possesses surprisingly little to say about these processes. Its analytical framework remains rooted in the notion of equilibrium in which the adjustment function revolves around price movements; that is, the idea that price movements guide economies back toward a condition of balance as “markets clear.” Disturbances are treated as temporary deviations from a centre of gravity to which the system naturally returns. The experiences of the Global Financial Crisis (2007-08), and the failure of the mainstream economics professional to “see it coming” is a recent example of conceptual blindness, but it isn’t the only case. Paul Krugman recently observed that:
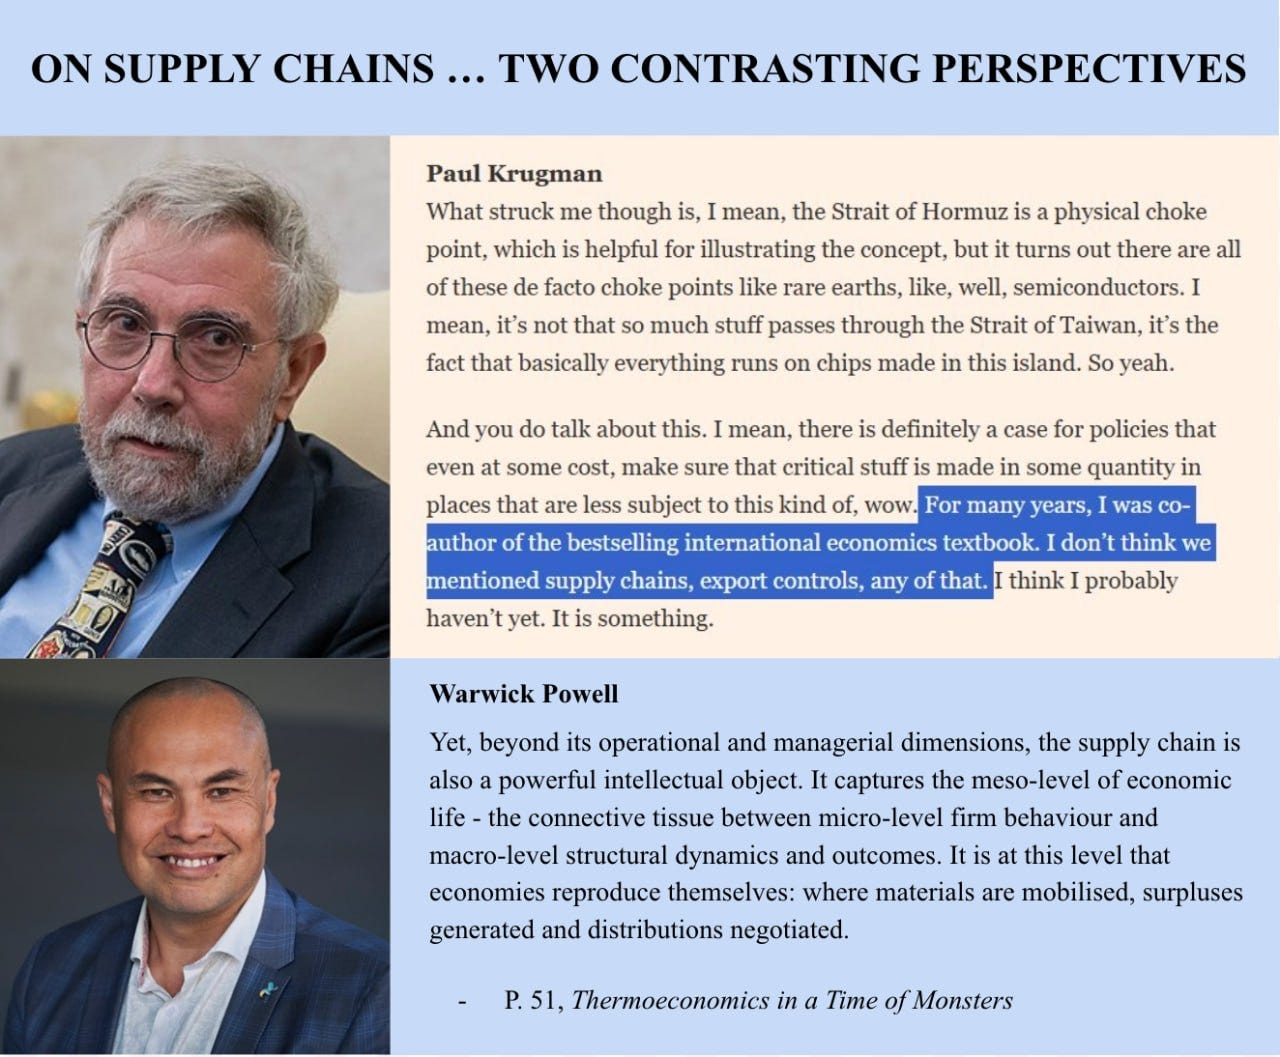
“What struck me though is, I mean, the Strait of Hormuz is a physical choke point, which is helpful for illustrating the concept, but it turns out there are all of these de facto choke points like rare earths, like, well, semiconductors. I mean, it’s not that so much stuff passes through the Strait of Taiwan, it’s the fact that basically everything runs on chips made in this island. So yeah. And you do talk about this. I mean, there is definitely a case for policies that even at some cost, make sure that critical stuff is made in some quantity in places that are less subject to this kind of, wow. For many years, I was coauthor of the bestselling international economics textbook. I don’t think we mentioned supply chains, export controls, any of that. I think I probably haven’t yet. It is something.”
It’s as if all of these disruptions have come as something of a shock to those who frame the world through mainstream equilibrium economic lenses, in which price adjustments act as the principal gravitational pull bringing the system back into balance. But what if there is no centre of gravity? What if instead of the detached abstractions of mainstream textbooks, supply chains actually mattered? What if economies are better understood not as systems seeking equilibrium but as systems seeking reproduction?
In my book, Thermoeconomics in a Time of Monsters, I argue in stark contrast to Krugman that:
… beyond its operational and managerial dimensions, the supply chain is also a powerful intellectual object. It captures the meso-level of economic life - the connective tissue between micro-level firm behaviour and macro-level structural dynamics and outcomes. It is at this level that economies reproduce themselves: where materials are mobilised, surpluses generated and distributions negotiated. (p. 51)
Seen from this perspective, the economy is not a collection of markets in which the principal question goes to “supply and demand” and the role of pricing in resource allocation. Rather, the economy is a web of interconnected supply chains extending across firms, industries and countries. Every output becomes somebody else’s input. Every sale is simultaneously somebody else’s cost. Every act of production depends upon a vast network of prior acts of production, and so on.
This simple but profound insight lies at the heart of the work of Piero Sraffa and the input-output analysis of Wassily Leontief. Sraffa recognised that production is inherently relational. The price realised by one enterprise becomes the cost incurred by another. There is no isolated market transaction. There are only interconnected processes of circulation and reproduction. Leontief transformed this insight into a formal framework. His input-output tables mapped the flows linking industries together, revealing economies as systems of mutual dependence rather than collections of independent sectors.
Curiously, much of economics moved in the opposite direction. The meso-layer of production networks — the connective tissue linking microeconomic behaviour to macroeconomic outcomes — largely disappeared. Analysis became divided between individual choice at one end and aggregate variables at the other.
Supply chains vanished from mainstream view. Recent disruptions have brought them back into public focus, even if the academics — a la Krugman — are only reluctantly now coming to the table.
Once we place supply chains at the centre of analysis, a different picture of the economy emerges. Economic systems appear not as equilibrium mechanisms but as nested structures seeking continually to reproduce themselves under changing conditions. Firms reproduce productive capacity. Supply chains reproduce material flows. Households reproduce labour power. States reproduce institutional arrangements. All are embedded within ecological systems whose constraints are themselves evolving.
There is no fixed destination. No natural resting point. No centre of gravity. Only systems adapting to changing circumstances and attempting to preserve the conditions necessary for their continued reproduction.
This shift in perspective transforms our understanding of scarcity.
Scarcity is not simply the textbook problem of unlimited wants confronting finite resources. It is a dynamic phenomenon reflecting changing patterns of relative resource availability. Shortages emerge in one part of the system and propagate through others. Adaptation in one location often creates new pressures elsewhere. Substitution may relieve a bottleneck in one industry only to increase demand pressures somewhere else.
Scarcity travels. Prices play a more complex role than either conventional economics or Sraffa’s original framework suggests. In neoclassical theory, prices are equilibrium signals. They coordinate supply and demand and guide economies back toward balance. Sraffa rejected this view. In his system, prices are primarily accounting outcomes expressing the underlying conditions of production and distribution. They record relationships rather than direct them. Yet, I suggest, once time and changing conditions are introduced, prices acquire a more active character.
A shortage of copper raises its price. That increase reverberates through the system because the price realised by one producer becomes the cost incurred by the next. Higher copper prices affect cable manufacturers. Rising cable prices influence electrical equipment producers. Construction costs increase. Investment plans change. Demand patterns shift.
Scarcity propagates through the network. Prices are therefore neither merely accounting identities nor purely equilibrium signals. They are both signals and carriers of propagation. They communicate changing conditions to economic actors while simultaneously transmitting disturbances through interconnected production chains. They do not restore equilibrium. They spread pressures as they represent claims being made by one set of agents on others.
Nor do firms simply react to realised cost increases. Businesses operate under uncertainty. They anticipate.
During periods of disruption, firms may raise prices in expectation of future cost increases. They may seek to rebuild margins eroded by previous shocks. In a broader inflationary environment, firms possessing market power may exploit the prevailing inflationary mood to pass through increases exceeding their immediate cost pressures. Once rising prices become widely expected, the inflationary climate itself becomes another mechanism through which price increases spread.
Expectations and institutions become layers of propagation. Inflation is therefore neither purely monetary nor merely the consequence of physical shortages. It emerges from the interaction of material constraints, financial pressures, expectations and market structures. The economy reveals itself to be simultaneously material and financial. Physical shortages become financial pressures. Rising costs compress margins and strain cash flow. Liquidity constraints influence inventories and investment decisions. Firms with limited access to working capital carry smaller buffers, increasing vulnerability to future disruptions.
Material and monetary processes become inseparable. Thermodynamics reinforces this perspective. Economic systems are physical systems. Production transforms energy and matter. Inventories are depleted. Machinery wears out. Skills decay. Energy is dissipated. Buffers consumed during periods of disruption require resources and time to rebuild. Irreversibility and path dependence are not anomalies. They are intrinsic features of economic life.
A useful way of understanding these processes is through a simple proposition:
Propagation occurs whenever the duration of a disturbance exceeds the duration of the buffers available to absorb it.
This principle applies throughout the economy.
Shortages of upstream materials constitute one form of disturbance. Their effects are initially absorbed by inventories. Firms draw down stocks accumulated during “normal” times. If shortages persist, profit margins are squeezed as businesses absorb rising costs rather than immediately passing them on. Enterprises seek substitute inputs or alternative suppliers, redirecting pressures elsewhere in the system. Eventually, if these adaptive capacities are exhausted, production is curtailed and demand itself is reduced.
Demand destruction becomes the final buffer.
The same principle applies beyond inventories. Cash reserves absorb financial shocks. Profit margins absorb cost increases. Spare capacity absorbs surges in demand. Credit provides temporal flexibility. Social institutions and state intervention act as collective buffers against disruption.
What matters is not simply the size of these buffers but their duration relative to the disturbances confronting them. Where disruptions are shorter than available buffers, propagation remains limited. Where disturbances outlast buffers, they spread. Inflation, shortages and recessions can thus be understood as different manifestations of the same underlying process: disturbances persisting longer than the capacities available to absorb them.
This is where the insights of Sraffa and Leontief acquire renewed significance. Their great contribution was to place production and interdependence at the centre of analysis. But their systems were largely comparative static. They described structures without fully explaining how disturbances move through them.
Introducing time, thermodynamics, finance and adaptive behaviour transforms the picture. Supply chains become dynamic systems. Scarcity changes. Buffers are consumed. Prices reverberate. Financial pressures emerge. Substitutions redirect strains. Expectations amplify or dampen responses. New bottlenecks arise. Firms adapt. Institutions intervene.
The system evolves.
The relevant question therefore changes. Instead of asking how markets return economies to equilibrium, we ask how disturbances propagate through interconnected systems and how those systems maintain their capacity for reproduction, or in part or in whole collapse.
Different societies possess different adaptive capacities because they possess different combinations of inventories, spare capacity, technological flexibility, financial resilience, institutional coordination and state capabilities. Resilience does not mean equilibrium. It means preserving the ability to reproduce. Indeed, equilibrium itself appears less as the normal condition of economic life than as a special case in which disturbances are perfectly absorbed.
Real economies inhabit no such world. They are continually adjusting to changing technologies, shifting demographics, evolving geopolitical relationships and fluctuating patterns of resource availability. The economy is not an equilibrium machine. It is an evolving metabolism. Prices, inventories, profits, liquidity and technologies are not equilibrium variables. They are state variables governing the propagation of disturbances through coupled material and financial networks. Equilibrium is merely the limiting case in which propagation is perfectly dampened.
The normal condition of economic life is continual adaptation, sometimes more successful than at other times. Understanding these propagation dynamics — and the capacities that allow societies to absorb, redirect and recover from them — may prove to be one of the central intellectual tasks of economics in the twenty-first century.
This is fascinating stuff, Warwick. It set me wondering what would happen to your theory if we, at every turn, focused on value chains rather than supply chains? Do we reach the same conclusions? I wondered if this question, this way of framing the core approach to analysing economic systems, wasn’t something that Krugman was reaching for. Or have I missed your and his point entirely?
Trade has been a human endeavor forever. Buying and selling are the nodes, there has always been “supply chains.” Long chains (Silk Road) or short - take your wool to the market town. Along the way, over history, society has reached a likely maximum of complexity, and there is no thought raised if a new hand reaches into a supply of any good or service - which is becoming a critical issue in times of resource constraint, reaching a “limit to progress.” Prices are simply an attempt to rectify a relationship between actual physical economy and the hyperfinancialized economy, what “the market” will bear. All the while the financialization sector is burdening the economy with interest payments. But simply viewing the overall economic flow (supply chains, etc.) misses the perspective that the extractive system is not merely consuming resource supply, it is hollowing out society’s metabolic base to feed the top. There is no possible repair mechanism. See also: https://theuaob.substack.com/p/the-trillionaire-siphon-why-the-bottom